September 2011 | Salt Spring Island Market Analysis

September, 2011.

Salt Spring Real Estate Market Update

As we are daily reminded: the only constant in life is change.

It’s also true that in change lies opportunity.

Our post-Internet time has obliterated time and so there is both no time, as in time famine, and also always time, as in never off.

With the search engine never asleep, and anything you want to know just a keystroke away, the power of the search now resides with the searcher…that means the consumer, in a sales situation.

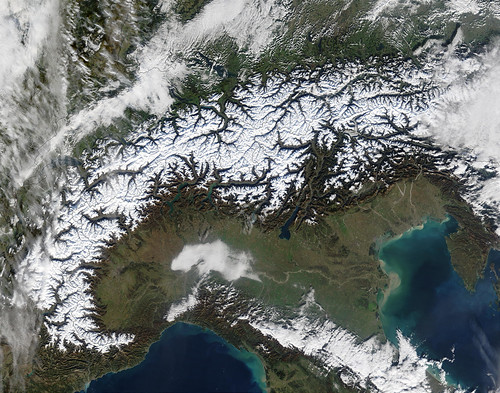
Switzerland

Switzerland via NASA (and flickr.com)

This has huge impact on all real estate in secondary home/discretionary areas, where the Internet has erased both time and geography, and where someplace is now in competition with everyplace…it becomes essential to market the area itself as well as the property located there.

someplace is now in competition with everyplace…

This encourages time lags in decision-making…the buyer has to first discover the area, then visit, then think about what it means to his/her lifestyle, compare it to other options, and then has to focus in on the actual properties of potential interest in the chosen area.

Time is a factor..,perhaps a purchase will take from one to five years in a discretionary area. If it seems to happen more quickly, it may simply mean that the buyer has already been through the above process, may be back for a third “look”, with months between visits, when suddenly a desired property comes on the market, at same time. That can happen!

Patience plus international marketing is the key for secondary home/discretionary/resort based regions..,and globally so.

We are now residing in Marshall McLuhan’s “global village”…a local buyer for a Gulf Island property might come out of Vancouver or Calgary or San Francisco or Toronto or Shanghai or Sidney or Auckland or London or Bern or..,you get the drift! “Local” doesn’t mean in your own backyard, anymore.

Throw in up or down market trends, currency valuations, deflation/inflation arguments…and there’s more “time lag” components!

Over time, an investment in a secondary home/discretionary area will appreciate…it’s a “long tail” investment, though, never a fix & flip.

As soon as a consumer is in charge of a process, time is a companion in a sales situation.

More info? Call me! And your thoughts are? Always welcome!

How may I help you buy your special Salt Spring Island or Southern Gulf Islands opportunity?

Call me!

August 2011 | Salt Spring Market Analysis

Copyright, Li Read, 2011

August, 2011.

Each month that passes, since that October to February 2010/11 timeframe, which may be looked back at as a “transition moment”, shows continuing slow but steady improvement in both showings action and in sales.

It is true that the main sales activity falls into what might be described as entry level residential. To date, undeveloped land, commercial/business options, cottage/retreat properties, and upper tier priced residential opportunities, remain “flat”.

It’s interesting to note, though, that the entry level pricings that found buyers, in 2009, were below $450,000. By 2010, this had crept up to $650,000. Now, we are seeing sales in the low to mid-700s.

There are random encounters in the $900,000 to 1.8 million range, with the higher tier being found in the oceanfront residential options, but they are few and far between, with little pattern developing as to a trend.

Price reductions have been a feature of our secondary home/discretionary marketplace for the past two to three years. Until very recently, these reductions did not result in more viewings or in offers. The buyer remained reluctant.

However. since it is essential to be seen as competitive in pricing, most sellers did reduce substantially over the past 18 month period. Some appraises feel that we reduced in pricings by around 30%, between mid-2007 and current date. With so few sales to point to, though, in any one category, it’s difficult to rely on this totally.

As of July 22nd, the weekly solds to date for 2011 saw the bulk of sales in residential, up to $680,000 (72 in total, up to $700,000, with over 50 of these sales coming in under $500,000). There were seven sales between $700,000 and $900,000. There were four sales between $900,000 and one million. Another four sales between one and two million. Only one sale over two million.

In most secondary home/discretionary regions, globally, there is always an inverted pyramid, I think, with the “affordable” entry level residential being a smaller inventory, and the higher end/luxury options being the majority…a different circumstance from a primary residence/city market.

In all discretionary regions, it has been slow in sales since early 2006. In January, 2007, the Wall Street Journal did note that all secondary markets were “stable/inactive” throughout 2006…they meant by this that inventory and prices remained stable and the buyer had become inactive.

So, in spite of all the worries afoot in our post-internet time, with change the constant mantra for all business, there are still cyclical patterns in markets…this is true for the stock market side of investment, and also so for the hard asset options (including real estate).

Although the city markets may not have calmed until late 2007/early 2008, Salt Spring and the Gulf Islands followed the global trend in all discretionary markets…we were “on hold” from that early 2006 moment. No one “has to” buy a second home or a retreat property or a future retirement option in any particular timeframe. It is always by choice. Since early 2006, then, the reluctant buyer syndrome has been present in all similar discretionary areas, around the world…the Fall, 2008 economic meltdowns just solidified for everyone/all markets just what that early hesitation dance had been about, in the secondary home / resort based regions.

Throughout 2009/2010, the sales were slow, were only residential, and mainly entry level pricings. In a downturn, no one is looking for a holding option or a building opportunity, and so undeveloped land does not attract interest. Houses are viewed (3 bed/2 bath), and that means a lack of interest in a recreational/cottage purchase. Higher priced residential lingers, too, as people hold cash…sometimes hoping that prices will come down further, and sometimes out of concern that cash is best to keep, if deflation wins out over the inflation scenario. That “argument” continues!

Underneath all of that worry over currency instability, and a seeking of a safe haven, which might be the driver to action in the rural and secondary home marketplaces right now, there is that cyclical nature of all markets. We may actually be in year six of a seven year cycle, which means we’re already on the way up. Savvy investor buyers may be acting now, while prices remain very soft, sellers are highly motivated, interest rates remain historically low, and there is good inventory choice in all property types/price ranges. Such purchasers may be of the opinion that the inflation scenario will be the winner of this lengthy argument between two outcomes…deflation vs inflation.

Whatever the reason, there is a difference out there right now. Locally, and for the first time in two years, we are seeing consistent interest, with physicality on Island to view options, not just phone calls or emails or facebook inquiries. In the viewing, it doesn’t mean an offer will come in, but the viewing has to happen first…good news, then, that there is this uptick.

Tourism has also increased, after a good two years of inaction. The marinas are busy with boaters, the galleries and markets in the park are busier, B & Bs and restaurants are busier, and the general “verve” of the Island does seem to have returned to 2007 levels. Good news all the way around, then.

Slow, yes, but it is steadily processing onward, and if this is year six, then we will see next year turning out to be very active and a start into Seller’s Market conditions again.

Nothing stays up or down, and equilibrium is a passing aspect…the sign of a transition moment. Perhaps that’s where we are, right this second?

Hmmm….

It appears, as well, that our local market will be brisk throughout August, September, October, and possibly into early November. A later / longer trend for this year. Perhaps a part of the year six moving into seven scenario? Always welcome your thoughts, too!

Looking for a Salt Spring Island or Southern Gulf Islands property? Call me! Successfully connecting buyers with sellers, since 1989, I look forward to bringing my expertise and knowledge (of both inventory and trends) to your benefit.

How may I help you to buy your special Island property?

Salt Spring Real Estate & Properties

Oceanfront Properties in Salt Spring

Real Estate in Salt Spring is primarily a place where buyer’s and seller’s make their second or even third home.

Johnstone Island

Johnstone Island

Johnstone Island | Oceanfront Estate

One such oceanfront property is the private island, Johnstone. The property enjoys all amenities (including power connected from nearby Vancouver Island), just mere minutes from protected Canoe Cove (a private marina), and yet with all the allure and privacy of your own serene world. (The island is so private that a search on Google is not likely to provide you with much information. Except maybe here).

July 2011 | Salt Spring Island Market Analysis

July, 2011.

Well, here it is…the “real season” has begun!

In the past, there used to be 3 “seasons” on Salt Spring & the Southern Gulf Islands: a short early Spring (Feb/March/early April), Summer (late May to early September), and the “off season” (October to January).

Tourism worked hard to keep activity consistent…events to bring attention to the Islands were stressing the “shoulder season” moments…different days, now!

Post-Internet, seasonality has been heightened. Someplace has become in competition with every place. The season in our region has shrunk to July/August/September, perhaps into early October.

The Gulf Islands/Salt Spring Island are not viewed as alluring winter venues…they are now seen as summer places.

The tourist visitor and prospective buyer (complementary streams of arrivals) go to Tucson, Palm Desert, Maui, Cabo…or the Caribbean…in the winter and enjoy the Pacific Northwest Coast in the summer…a skier might have a fractional ownership condo in Whistler or its equivalent, but main winter holidays would be in a sunny locale.

The Internet erased time & geography, & created Marshall McLuhan’s proposed “global village”.

Someone in the U.K. can enjoy a home in Spain, for winter vacations or seasonal retirement. Someone in Texas can escape the searing summer heat by retreating to a summer home on Salt Spring Island.

You get the drift…the entire world is now available to anyone…Chinese buying in Vancouver…or in Australia…or in Paris. Albertans buying in Scottsdale or Palm Springs . Brazilians buying in Florida….

What did I say? Some place is now in competition with every place?

It is essential to market to a breadth of potentials, to get the information out to where the buyer “is”…& then to create interest in the specific area, so that the buyer will choose the Island over Tofino or Qualicum or Sechelt or Kelowna or…anywhere at all.

Why here? Why not there? Time lags become more evident, as choice grows!

This is an amazingly beautiful part of the world, & the Southern Gulf Islands are in the heart of the best protected boating waters in this world.

The form of government, the Islands Trust, has a mandate of “to preserve & protect“, the environmental beauties of these island gems, for the benefit of all B.C. residents…their bylaws/zonings control growth.

No market stays up or down, and rarely “holds” in equilibrium. In the cyclical nature of a market, we may be in year six of a seven year downturn…which means we’re already on the way back up.

It may be that we will look back & decide that Sept/October, 2010, were the “bottom-bottom” of the market…certainly, savvy investor buyers were active then.

It’s not too late to act. Low interest rates for now, still motivated sellers, good inventory to choose from, price reductions around 30% from 2007 to present day…all of the above intertwined with a seeking of a safe haven and a concern over currency instability…sounds like an ideal time to turn to a good hard asset investment, for preservation of capital.

Hmmm…the societal shifts delivered by the Internet continue to work themselves out, and no endeavor is untouched.

Looking for your Island paradise? Call me! Successfully connecting sellers and buyers, on Salt Spring & on the Southern Gulf Islands, since 1989, it’s important to me that your best interests are promoted…I look forward to bringing my knowledge & expertise to your benefit.

Farms, waterfronts, acreages, view properties, commercial enterprises, investments for appreciation, private islands…I look forward to introducing you to your special opportunity.

How may I help you to buy your special Salt Spring Island or Gulf Island property?

Copyright, Li Read, 2011

June, 2011 | Salt Spring Island Market Analysis

Copyright, Li Read, 2011

June, 2011 | Market Analysis

The Beginning of the Real 21st Century

Some mid-year market “thoughts”….

On my last count, there appear to be 32 realtors still in the business, on Salt Spring Island.

When I first started as an Island realtor, in 1989, there were 9 companies and 89 realtors in the business. Some realtors were, of course, part-time (by choice). I learned what that 80/20 “maxim” was all about: 80 % of the business is done by 20% of the people. This truism applies to all business, I think.

Between 1994 and 1998, in B.C., there was a significant downturn…the rest of North America appeared to be booming away, economically, but not B.C.

At that time, it was against the Real Estate Act in B.C. to have another job…one was a realtor and that was that.

In downtimes, then, with endless expense/no incoming, realtors often “hung up their licenses”, for the allowable two year period, and did something else, hoping to wait out the poor sales time. The Real Estate Services Act, which recently replaced the old Act, did introduce some changes. Another change allowed realtors to hold a second job, and a job without any relationship to real estate sales…this does allow realtors the option, then, of keeping their licence intact, while working at another job, during a downturn. Such a decision might lead to a part-time sales status, which means information might not always be optimum/of the moment. A struggle, perhaps, on the part of the agent, to remain “current” while not actively pursuing the real estate sales side of their careers.

Also, before 1998, it was often valuable to work for a major franchise company…although offices were usually owned/operated “locally“, they had an “umbrella” association with each other. Pre-Internet days, this loose federation of offices did encourage referrals between offices, and that was occasionally a “plus” for the realtors working for such “label” firms.

The advent of the Internet erased that small advantage, however.

In 2000, several things occurred, although no one was connecting the dots, and realizing that a major shift was underway.

THE DOT.COM BUBBLE BURST, and a lot of money was looking for a home. The Internet had erased time and geography, putting information searching in the control of the consumer (not the company or the agent), and this “international “not “local” buyer profile was seeking solid investments.

At the same time, we had historically low interest rates, coupled with easy mortgage money, and a very low Canadian Dollar compared to U.S. Dollar, British Pound, and Euro currencies.

The Internet search had also helped to propel the discovery of the beauty of the entire Pacific Northwest Coast, a long overlooked area…and one with some of the best protected boating waters in the world!

Between 2000 and 2002, sales volume rose by approximately 50%, according to some appraisers. The 9/11 horror added a new component to a buyer’s search parameter: the seeking of a safe haven….

Between 2002 and 2005, sale pricings rose approximately 60%, in many coastal communities, according to some appraisers, and especially in the Tofino/Uclulet area, on Salt Spring Island, in Whistler, and in B.C.’s Interior (Kelowna). Of course, per usual in “good times”, the ranks of realtors increased!

From the outside looking in, this career choice looks easy. It is, however, a business like any other, and there is a huge expense/outlay before any income is netted. That 80/20 “rule” is seen here, too: within two years of being licensed, 80% of new realtors have apparently left the business. In spite of a change to the Act, which now allows a realtor to hold a second job while licensed as a realtor, the expenditures of money, time, energy are still not for everyone.

Throughout 2006 and 2007, and into early 2008, there was a distinct “pause” in sales action. Prices began to soften as this slower time period evolved. The economic meltdowns of Fall, 2008 signaled the shift moment to everyone, not just to the savvy projectionists.

We are now firmly in the post-Internet world, where the consumer is in control and it’s a bottom up scenario, not a top down script. It’s perhaps the

beginning of the “real” 21st Century.

For real estate, this means we need to connect directly with our client base. Referral/umbrella franchise companies are a 20th Century model, and no longer provide the service they were created for…connections are now direct.

The buyer profile is international…geography is no longer a limiting factor, again due to the Internet. This means that a property somewhere is in competition with a property everywhere. One has to sell the area now, not just the property…the global village citizen has huge choice. Why here? Why not there? Sellers and realtors have to pay attention to this consumer choice scenario.

Time is erased…important to have data available “always”. his means new ways of presentation and availability have to be implemented. The great eye of the Internet search never sleeps!

Hmmm…in change lies opportunity, remember!

So, locally, baby steps of recovery in entry level residential options, throughout 2009 and 2010…just very recently a resurgence of interest in the luxury priced property segment…perhaps a fear of currency instability and a continued search for a “safe haven” are two drivers to action right now?…and, of course, recognizing that markets are always cyclical, we might be in year six of a seven year down cycle. That means it’s still a good time to be a buyer, but not for much longer…by 2013 we may be back to sellers market conditions.

My definition of a buyer’s market? High inventory, low prices, no buyers. A seller’s market? No inventory, high prices, lots of buyers. It’s buyers that set markets, not sellers or realtors.

I think we will look back and decide that October, 2010 was the “bottom-bottom” in the real estate market. I think by this time in 2012 we will see sellers back in control of the sales equation. It may be as a result of a shift to good hard asset investment to preserve capital, or simply that it’s the beginning of the next seven year cycle.

Looking for an excellent property investment on Salt Spring Island?

On another Gulf Island?

On Southern Vancouver Island?

Call me!

It’s important to me that you “buy well”. It’s all beautiful, but it’s not all “equal”.

I can also refer you to a good realtor in another area of B.C., if that’s your preference.

How may I help you to buy your special property?

Look forward to connecting with you!